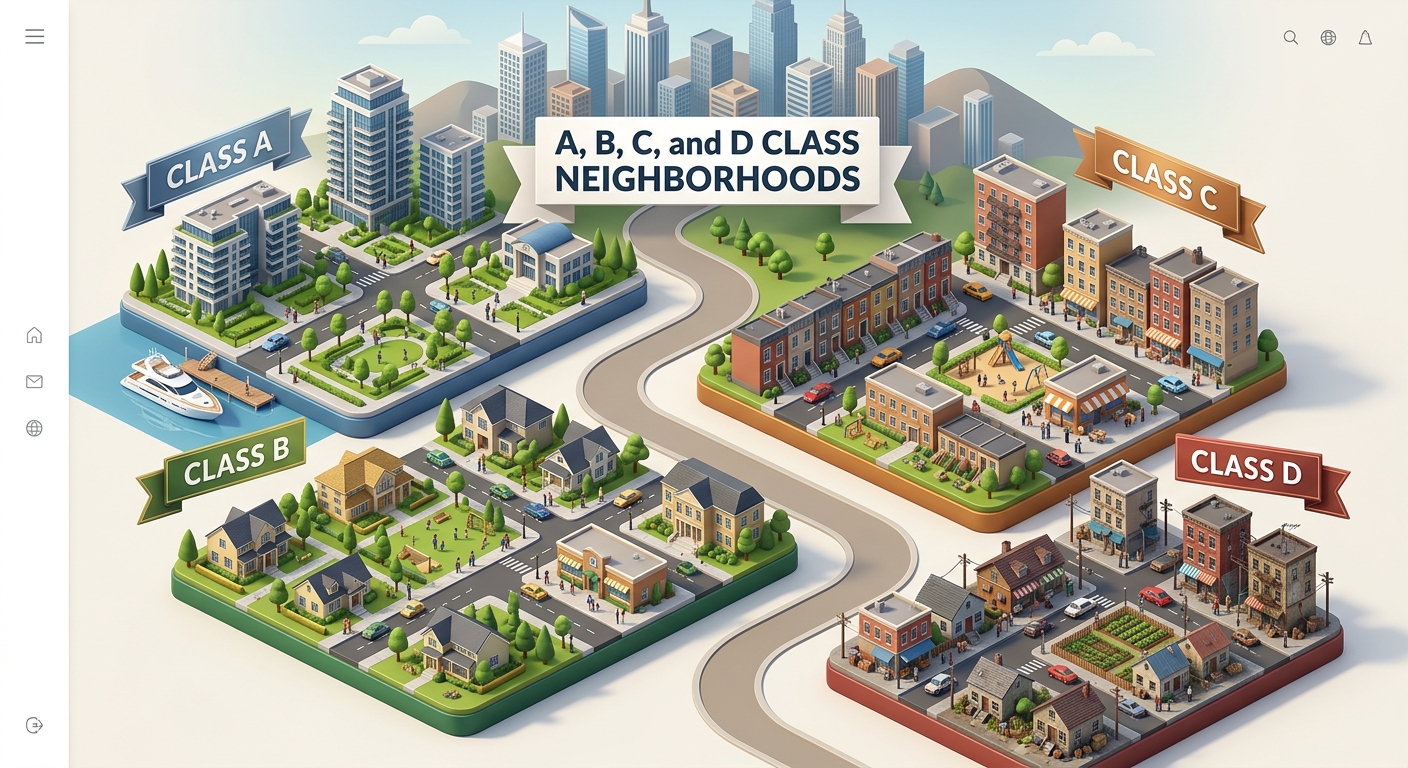
A, B, C, and D Class Neighborhoods
Real estate is hyper-local. A 10% cap rate in a Class D neighborhood is vastly different from a 5% cap rate in a Class A neighborhood. For more data on this, see HUD.gov.
| Class | Characteristics | Typical Investor |
|---|---|---|
| Class A | New build, luxury, prime location, low cap rate | Institutional, low-risk |
| Class B | 15-20 years old, solid working class, reliable | Balanced yield/appreciation |
| Class C | 30+ years old, needs repairs, higher turnover | Cash-flow focused, hands-on |
| Class D | High crime, deep distress, paper returns look amazing | Specialists only |
The Sweet Spot
A Deeper Dive: Why This Matters Now More Than Ever
In today's rapidly evolving real estate market, standing still is the equivalent of falling behind. As institutional investors deploy billions of dollars into single-family rentals and multi-family syndications, the everyday independent investor must rely on sharper underwriting, tighter operational efficiencies, and a deeper understanding of macro-economic trends. It is no longer sufficient to simply look at a property and guess its potential; you must model it meticulously. For more data on this, see BiggerPockets.
Consider the impact of shifting interest rates. When the cost of capital increases, the margin for error dramatically shrinks. A deal that would have easily cash-flowed at a 3% mortgage rate might bleed money at 7%. This forces investors to seek out higher-yielding properties, often moving from Class A and B neighborhoods into Class C, or executing heavy value-add strategies to force equity creation. For more data on this, see Urban Land Institute.
“The most successful investors don't predict the future; they underwrite so conservatively that they survive regardless of what the future holds.”
Common Mistakes and Pitfalls
One of the most frequent errors we observe is "spreadsheet bias"—the tendency to torture the numbers until they tell you what you want to hear. If a deal requires a 0% vacancy rate and zero maintenance costs to break even, it is not a deal; it is a liability waiting to happen. For more data on this, see Roofstock.
- Underestimating Capital Expenditures (CapEx): Roofs, HVAC systems, and foundations do not last forever. Failing to reserve cash for these massive expenses is a recipe for disaster.
- Ignoring Local Legislation: Rent control laws, eviction moratoriums, and strict zoning ordinances can completely alter the profitability of a strategy.
- Over-Leveraging: Taking on too much debt leaves you incredibly vulnerable to market downturns and extended vacancy periods.
Operational Reality Check
Actionable Steps to Implement Today
Knowledge without execution is merely entertainment. To truly benefit from this strategy, you must begin implementing these principles immediately. Start by analyzing your current portfolio or, if you are new, by underwriting at least three mock deals per day. This builds the "muscle memory" required to spot a genuinely good opportunity the moment it hits the market. For more data on this, see Investopedia.
Furthermore, focus on building your team. Real estate is a team sport. You need a rock-solid contractor, a savvy real estate agent who understands investor needs, and a property manager who treats your assets like their own. Without this triad, scaling becomes nearly impossible and infinitely more stressful.
Conclusion and Next Steps
Ultimately, success in real estate investing comes down to a combination of education, disciplined underwriting, and relentless execution. The concepts outlined here are foundational—they are the bedrock upon which massive, generational wealth is built.
We highly recommend using tools like Dwelize to accelerate your analysis. By instantly calculating ARV, cap rates, and cash-on-cash returns, you remove the emotional bias from your acquisitions and rely purely on the data. Keep underwriting, stay disciplined, and your portfolio will grow.