How to Analyze a Rental Property in 20 Minutes: A First-Pass Checklist
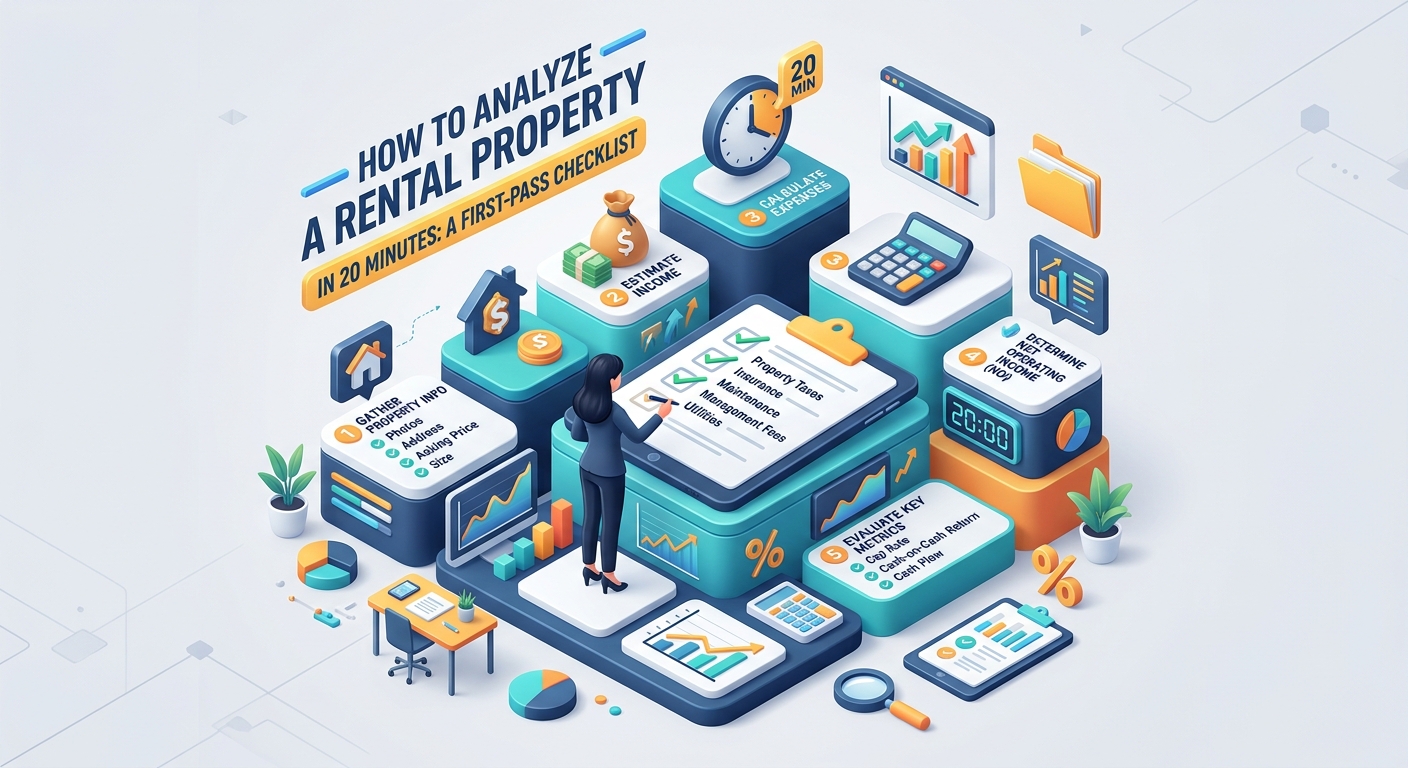
A 20-minute rental property analysis is not due diligence. It is a disciplined first screen that helps you decide whether a listing deserves another hour, a call to an agent, and eventually professional review.
Use this as a screening framework
Why this matters now
Fast-moving listings create pressure to decide before every document is available. A repeatable first-pass process keeps speed from becoming guesswork and makes it easier to compare several properties using the same assumptions.
The goal is not to predict one perfect outcome. It is to identify which assumption would hurt the deal first, make that assumption visible, and decide whether the remaining margin is worth the risk.
The framework at a glance
| Minute | Check | Output |
|---|---|---|
| 0–3 | Address and listing facts | Property type, condition clues, asking price |
| 3–7 | Rent evidence | Conservative monthly-rent range |
| 7–11 | Operating costs | Tax, insurance, vacancy, maintenance placeholders |
| 11–15 | Financing | Payment and cash-invested estimate |
| 15–18 | Value and comps | Questions for an ARV / comp review |
| 18–20 | Downside case | Reason to continue or stop |
A table is only useful when every input has a source or an explicitly conservative assumption. Label estimates as estimates; do not quietly turn a hope into a fixed number.
A practical walkthrough
Start with the address and ask a smaller question than “is this a good deal?”: can this property plausibly meet your buy box under conservative rent and financing inputs? If the first pass fails, do not rescue it by shrinking vacancy or repair reserves. If it passes, write down the two facts that need verification next.
- Capture the listing price, beds, baths, square footage, property type, and any visible repair clues.
- Find multiple rent references and use the lower credible end until you have better evidence.
- Enter tax, insurance, vacancy, maintenance, and repair assumptions explicitly.
- Model financing with the terms you can actually obtain, including cash invested.
- Review cash flow, cap rate, cash-on-cash return, GRM, and break-even rent together.
- Make a clear next action: reject, investigate, or prepare an offer range.
After each step, write down what would change your mind. That turns underwriting into a repeatable decision process instead of a spreadsheet that confirms a property you already want to buy.
Common mistakes to avoid
- Spending twenty minutes looking for a perfect number instead of identifying the highest-risk unknown.
- Comparing a renovated comp to an unrenovated subject without noting the condition gap.
- Skipping insurance, taxes, and maintenance because the listing does not include them.
- Treating the first-pass output as a purchase recommendation.
Do not optimize one metric in isolation
Turn the lesson into an underwriting habit
Run the base case first, then test a downside case before you become attached to the property. For a rental, that usually means pressure-testing rent, vacancy, maintenance, financing, taxes, insurance, and upfront repairs.
Use the Dwelize rental property calculator for a transparent first pass, then analyze a real address when you need a report workspace, an editable valuation workflow, comparable properties, and sharing.
Related reading
- Six numbers investors review before buying reinforces the value of a consistent metric set.
- Use the sample report to see how a full analysis is organized.
- Read What do I need to enter? before creating your first report.
For definitions of the underlying metrics, see cap rate, ARV, cash-on-cash return, GRM, and the underwriting FAQ.