Break-Even Rent Explained: How Much Cushion Does Your Rental Deal Have?
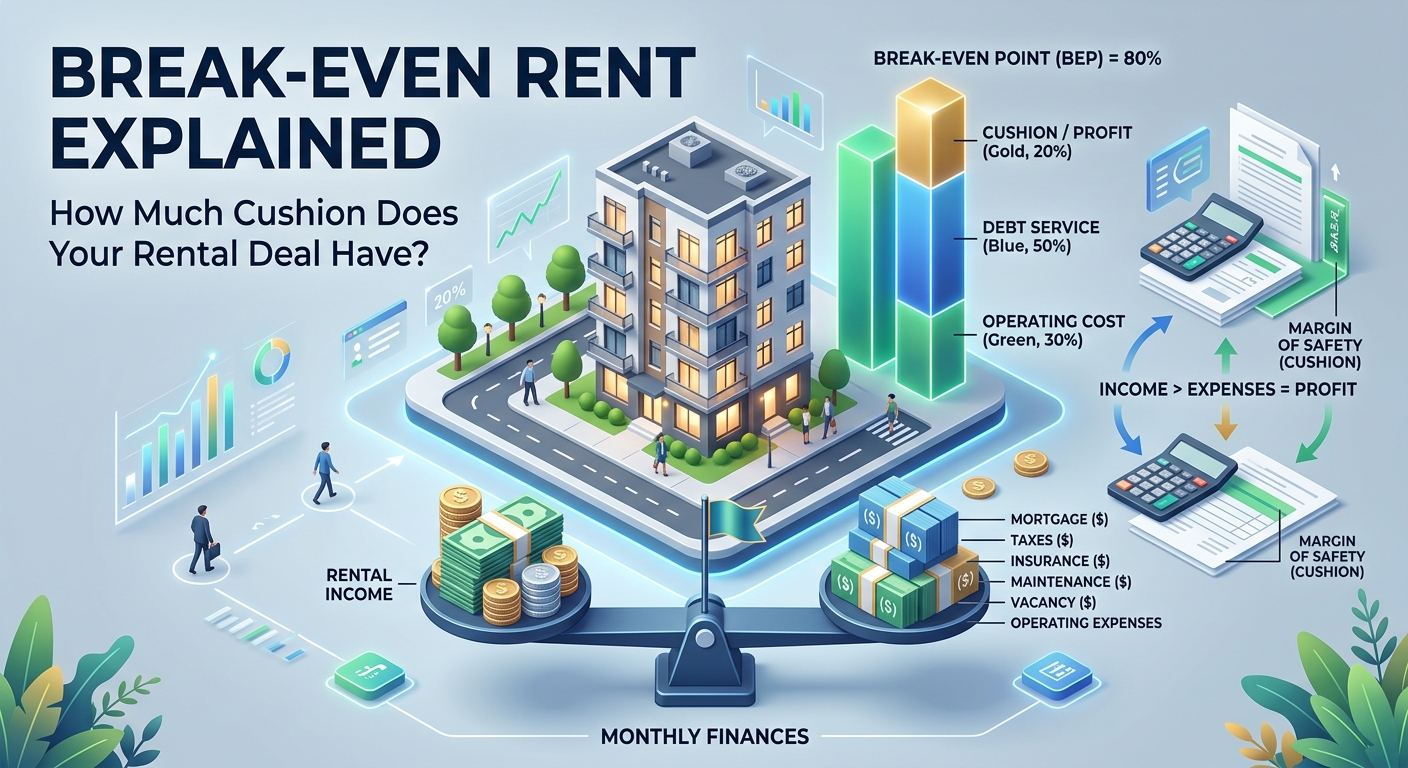
Break-even rent answers a practical question: how much monthly rent does this property need to cover the recurring costs you modeled? It is not a forecast, but it is a direct way to see how much room exists between the market-rent assumption and the deal’s operating burden.
Use this as a screening framework
Why this matters now
A property can appear safe when projected rent is high, yet have little tolerance for a renewal concession, a longer vacancy, or a higher insurance bill. Break-even rent turns those pressures into a number you can compare with credible rent evidence.
The goal is not to predict one perfect outcome. It is to identify which assumption would hurt the deal first, make that assumption visible, and decide whether the remaining margin is worth the risk.
The framework at a glance
| Component | Effect on break-even rent | What to verify |
|---|---|---|
| Mortgage payment | Higher payment raises required rent | Rate, loan amount, term, fees |
| Property tax and insurance | Higher annual bills raise required rent | Address-specific current and post-purchase estimates |
| Vacancy and maintenance | Higher reserves raise required rent | Local operating history and property condition |
| Market rent | Does not change break-even itself | Determines the cushion above it |
A table is only useful when every input has a source or an explicitly conservative assumption. Label estimates as estimates; do not quietly turn a hope into a fixed number.
A practical walkthrough
If your break-even rent is $1,800 and credible rent evidence is $2,200, the gross cushion is $400 per month. That is more informative than “positive cash flow” alone because it tells you how much rent movement the modeled deal can absorb before costs outrun income.
- Calculate the base case with your actual financing and operating assumptions.
- Record the break-even rent next to a conservative rent range—not one optimistic estimate.
- Test what happens after a rate, tax, insurance, vacancy, or maintenance change.
- Ask whether the cushion is sufficient for your risk tolerance and reserve policy.
- Revisit the number after inspection, loan terms, or rent evidence changes.
After each step, write down what would change your mind. That turns underwriting into a repeatable decision process instead of a spreadsheet that confirms a property you already want to buy.
Common mistakes to avoid
- Confusing break-even rent with a recommended asking rent.
- Ignoring management, utilities, or reserves that belong in your operating model.
- Using gross rent without a vacancy assumption and calling the result conservative.
- Assuming a large cushion eliminates the need for cash reserves.
Do not optimize one metric in isolation
Turn the lesson into an underwriting habit
Run the base case first, then test a downside case before you become attached to the property. For a rental, that usually means pressure-testing rent, vacancy, maintenance, financing, taxes, insurance, and upfront repairs.
Use the Dwelize rental property calculator for a transparent first pass, then analyze a real address when you need a report workspace, an editable valuation workflow, comparable properties, and sharing.
Related reading
- See the rental calculator for a live break-even-rent calculation.
- Compare it with GRM, which is faster but does not include operating costs.
- Review cash-on-cash return after you understand the property’s monthly cushion.
For definitions of the underlying metrics, see cap rate, ARV, cash-on-cash return, GRM, and the underwriting FAQ.