Off-Market Offer Calculator: Build Your Maximum Price From the Bottom Up
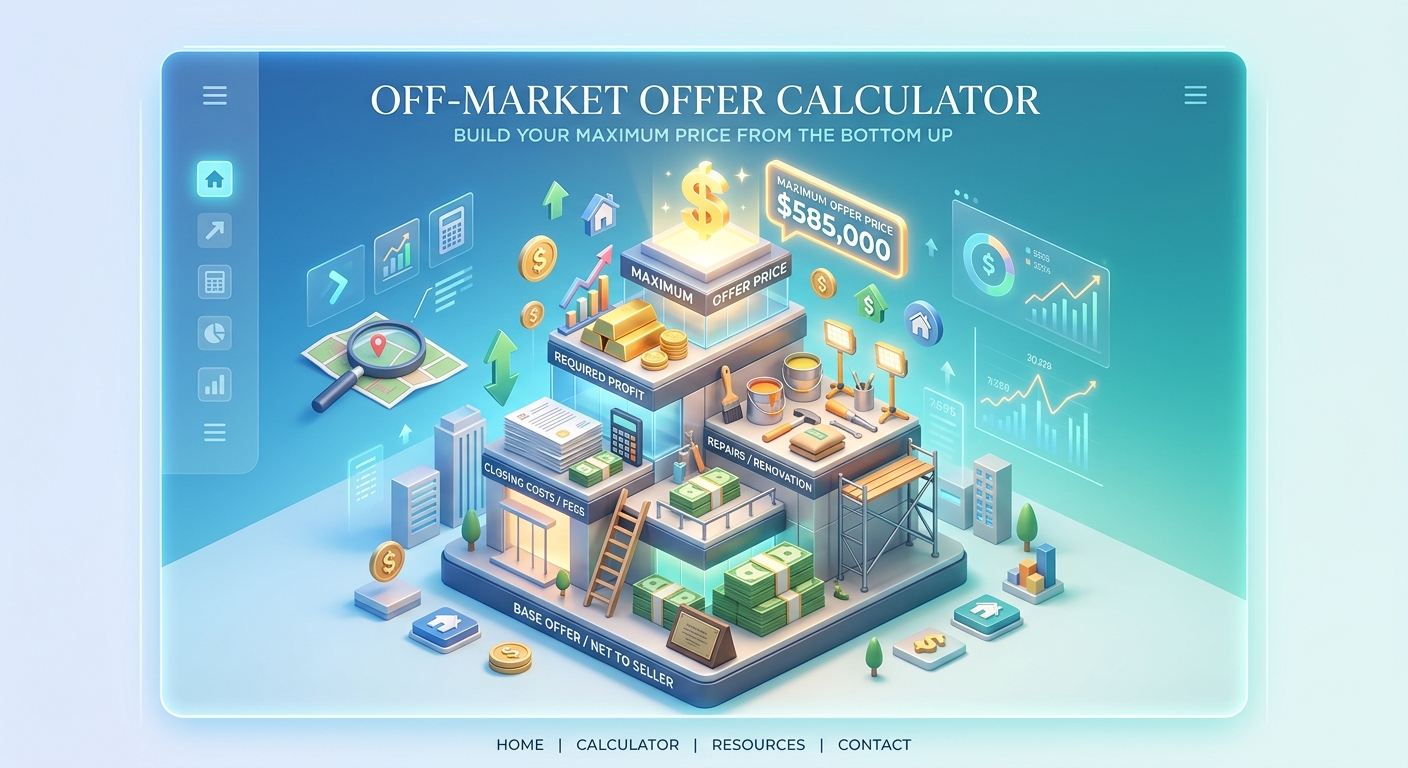
An offer calculator should not manufacture a “maximum allowable offer” by hiding assumptions. Its job is to make the assumptions visible. Begin with the investment strategy—rental, flip, BRRRR, wholesale, or turnkey—then work backward from a conservative income or exit scenario, all-in costs, financing, reserves, and the margin your strategy requires.
Off-market does not mean unverified
What “off-market” really means
Off-market usually means the property is not being broadly marketed on a public multiple-listing service at the moment you find it. It does not automatically mean below-market pricing, a motivated seller, a clean title, or a simpler closing. It only changes the acquisition channel. The investor still has to establish why the seller may transact, what the property is worth, and whether the operating case survives a conservative downside test.
That distinction matters because off-market opportunities often arrive with less structured information. A listing may include photographs, taxes, square footage, disclosures, and an asking price; a direct conversation may include only an address and a story. Treat missing data as an item to verify, not as permission to fill the gap with the most favorable assumption.
How to find and qualify the lead
Before discussing price, collect the basic facts: property size and condition, occupancy, seller timeline, likely repairs, taxes, insurance, rent evidence, comparable sales, financing availability, and transaction structure. If you do not yet have access, calculate a preliminary range and label it as preliminary. Do not imply that a range is a final offer until facts are verified.
- Write the strategy and intended holding period at the top of the model.
- Enter conservative ranges for the inputs least certain today.
- Calculate all-in cost before comparing to rent or ARV.
- Run base and downside cases, then state the maximum price range each case supports.
- Use inspection, title, financing, and comp findings to update the range before final negotiation.
The numbers before the conversation gets expensive
For a rental, calculate monthly income after vacancy and operating costs, then subtract debt service and reserve needs. For a flip, calculate projected sale proceeds less purchase, repairs, financing, holding, and selling costs. For every strategy, total acquisition cost matters more than headline price. Use the Dwelize calculator to expose the assumptions and then preserve the notes behind each number.
| Calculation layer | Rental example | Flip example |
|---|---|---|
| Revenue / value | Conservative monthly rent | Conservative resale / ARV |
| Acquisition | Price + closing + repairs | Price + closing + repairs |
| Operations / hold | Vacancy, expenses, debt service | Interest, taxes, insurance, utilities |
| Exit | Stabilized cash flow and refinance path | Selling costs and timeline |
| Decision | Return + break-even cushion | Margin after all costs |
Use ranges during the first pass. A low, base, and high repair estimate is more honest than one precise number obtained before an inspection. Do the same for rent, vacancy, insurance, financing, and closing costs. If the deal only works at the most optimistic end of every range, it is not yet an actionable deal.
Do not confuse a discount with a deal
Compare the off-market route with the public market
A fast percentage rule can help sort a large list, but it cannot replace address-level taxes, insurance, condition, rent, loan terms, and exit costs. A detailed model takes longer but reveals why two similar purchase prices can create very different outcomes. Use the quick rule to decide what deserves a model—not to decide what deserves a contract.
A repeatable decision process
Start by recording the source of the lead, the seller’s stated timeline, and the facts you have actually verified. Then create a first-pass Dwelize report using conservative price, rent, and operating assumptions. The report is not a substitute for inspection, title work, professional advice, or a local agent; it gives the conversation a clear numerical baseline.
Next, decide which fact would most change your offer: repair scope, rent, value, title, financing, or timeline. Obtain evidence for that fact before negotiating around a final number. This approach is slower than sending a blind offer, but it prevents an apparent sourcing advantage from becoming an underwriting disadvantage.
Common mistakes
- Using ARV or rent as a precise fact before checking relevant comps.
- Excluding closing, holding, financing, selling, or reserve costs.
- Letting the seller’s asking price anchor the model.
- Using a maximum price as an obligation to offer that amount.
“The advantage in off-market acquisitions is not secret access. It is a repeatable process for turning incomplete information into a disciplined decision.”
Next steps and related reading
Build a simple acquisition log: lead source, contact date, property facts, asking price, estimated total cost, verified rent range, key unknown, and next action. Review the log weekly. Over time it shows which channels generate conversations, which generate offers, and which actually generate closings—three very different measures.
For the supporting calculations, use the rental property calculator, then compare cap rate, cash-on-cash return, ARV, and break-even rent. Every number should remain a decision aid, not a promise of performance.